


What Comes After the NRRP? The PPNR: €60 Billion in Public Investment
Romania is closing out its National Recovery and Resilience Plan (NRRP) with more than 90% of its grants salvaged, but without the competitiveness leap the programme promised. For 2028–2034, the National and Regional Partnership Plan (PPNR) brings at least €60 billion in non-reimbursable funds, more than four times as much. What is at stake with this money is already a subject of discussion between politicians and the business community. If we repeat the mistakes of the NRRP, the PPNR won’t help us much either.
A Two-Sided Balance Sheet
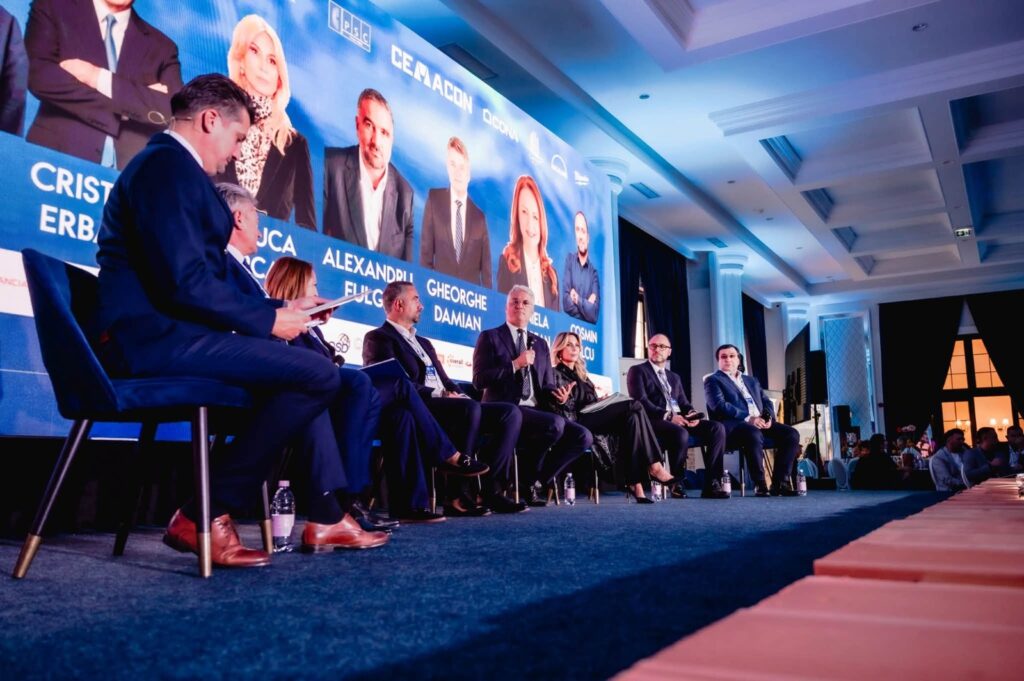
On Friday, at a conference in Sibiu on construction and the capital needed to deliver infrastructure projects, the Minister of Investments and European Projects, Dragoș Pîslaru, started with the numbers. In June 2025, the NRRP stood at 45%, stuck in negotiations with the European Commission, with large debts owed to builders. Now, Romania estimates it will collect more than €12.2 billion of the €13.57 billion in grants. Loan absorption will reach 95% or more, and some projects have been moved to other funding sources: ten hospitals to cohesion funds, and the motorway segments towards Ukraine and Moldova to the SAFE programme. What was the NRRP? “Not a success, but quite simply a miracle.”
Pîslaru acknowledged, however, that the result is only partial: it was “a race against the clock, more about staying afloat,” not an opportunity for Romania to “shoot ahead competitively.” The “stop and go” pace, with delays, legal challenges and uncertainty, prevented the construction sector from building up its capital. And the NRRP was not a national programme, but “a potpourri” of isolated investments.
From the builders’ perspective, the difference between the NRRP and the PPNR also lies in a change of philosophy. Here I would paraphrase Cristian Erbașu, who summed up the difference between the programmes perfectly. In previous programmes, “you submitted the invoice, you got the money.” From now on, however, payment comes only when targets are met. His lesson: rather than signing contracts beyond the available budget, it is better to go for mature projects that can be finished on time.
“A PNRR on Steroids”
The 2028–2034 programming period brings all European funding sources together in a single plan. Romania is set to receive at least €60 billion in non-reimbursable funds, perhaps €40 billion if the EU budget is cut during negotiations. Pîslaru proposed a “1-1-1” formula: for every European euro, one euro from the state budget (around €10 billion a year) and one euro of private capital. That would add up to an ambition of roughly €200 billion, with the targets of a trillion-dollar economy and euro adoption by 2034.
The minister warned that if the new plan once again becomes a “big share-out,” the targets will not be met. The change he proposes for companies is fundamental:
- at least one third of the money would go directly to the private sector, compared with a maximum of 20% so far;
- companies will no longer submit their business plans to the ministry, but will turn to the banking system for validation and financing;
- banks will receive blended finance instruments, with grants of up to 40%, interest subsidies and guarantees;
- the Investment and Development Bank will be at the centre, and the ministry is already testing 27 financial instruments.
Public-private partnerships are coming too. A portfolio of ten hospitals, including Sibiu County Hospital, is being prepared as a PPP with assistance from the EBRD, following the Greek model. The minister’s argument: with the same budget, the state can build ten hospitals instead of five.
Equity or Competitiveness
There will be money. But who will make the hardest decision? Who will be able to say how the money is split between equity — that is, roads, water and sewage, and rural communities left behind — and competitiveness — that is, AI, drones, dual-use and European value chains? We will still have only 100% of €60 billion to divide.
The 2027 Gap
The most concrete concern, however, again comes from the construction sector: what happens to the 500,000–600,000 people mobilised to the maximum for NRRP projects while the new plan is being negotiated? In fact, for construction entrepreneurs, the gap between the NRRP and the PPNR is of capital importance. If this gap cannot be covered by cohesion funds or other financing, times will not be easy for one of the sectors with the largest share of Romania’s GDP. Even though absorption has risen from 4% to 36.5% in a year and a half, about €17 billion of the €31 billion remains, of which, in order not to put the brakes on Romania’s major builders, we should draw down €10 billion, compared with €6 billion under the current forecast. The money should go to open construction sites in transport and water and sewage, which risk being left without funding.
Allow me to make a recommendation, which is in fact standard, ordinary practice in the world of private investment. What if the new national plan had to pass four investor questions:
- How many private euros does each public euro attract?
- What measurable revenues or savings does it generate?
- Who pays the operating costs over ten years?
- What capacity remains in the economy after the project ends?
“1 euro from the EU, 1 euro from the budget, 1 euro from the private sector” is the thesis Minister Pîslaru champions, with the ambition of raising €200 billion over the next seven years. He also proposes moving corporate financing from the ministry to banks, equity funds and the capital market. In this context, the Investment and Development Bank (BID) would sit at the centre of the architecture, with an EIF-style fund of funds, a blended finance arm (up to a 40% grant component, interest subsidies, guarantees) and joint ventures for strategic projects. It is an ambitious thesis, but one anchored in reality and one that could be achieved. All the more so since, on 25 June 2026, the European Commission approved a €1 billion capital increase for BID, the extension of the state guarantee until 2032 and the expansion of its mandate to strategic sectors. Government Emergency Ordinance (OUG) 8/2026 allows BID to participate in investment funds alongside international financial institutions and private pension funds. Pension funds may invest up to 1% of their assets in private equity, a ceiling that can rise to 5% where the state or BID holds stakes or where the funds are financed through the NRRP. This is the concrete bridge through which a viable circuit can be built between BID, Pillar II pensions and the capital market, with the aim of multiplying the money injected into the economy.
So the capital for the next investment cycle can also come from the capital market, not just from budgets and grants. If we are talking about instruments linked to stock-market capitalisation, the idea translates into three concrete directions.
First: project bonds and municipal bonds, listed on the stock exchange, through which local authorities can fund their co-financing without waiting for transfers from the centre.
Second: listed infrastructure funds, with pension funds coming in as anchor investors, placing long-term savings in long-term assets such as motorways, PPP hospitals or utility networks.
Third: listing builders and materials producers, so that the sector raises capital from the market rather than through supplier credit. This is the direct answer to the problem raised by Cristian Erbașu, that Romanian companies “are not that well capitalised,” and to the one described by Cosmin Vîlcu, of the builder who “becomes a bank” for public beneficiaries.
An industry with access to equity could take on PPP projects, join European consortia and more easily withstand a financing pause, such as the gap looming in 2027.
But until then, what do we do about political and regulatory risk? This risk has a price, and someone pays it. Either the state takes it on, through stability clauses, guarantees and mandatory interim deadlines, or the private sector prices it into its returns and everything becomes more expensive. You cannot ask the private sector for a third of the capital while leaving it 100% of the risk.